Retiree loans: repayments can now take 40% of net pay, up from 30%
The Central Bank brought pensioners in line with employees, and lenders must show what is left each month.
The Central Bank of Kuwait has changed its rules on consumer and housing loans and credit cards. Retirees can now commit up to 40% of their net monthly pay to loan instalments, up from 30% — the same ceiling that already applied to people in work. The circular went to banks, investment companies and finance companies on the evening of Wednesday 11 November 2026.
What changed
Until now the rules split the two groups: 40% for employees, 30% for retirees, as the bank’s own FAQ page still states. The amendment removes the gap. The bank says the aim is equal treatment and wider access to finance.
The circular also touches insurance charges, changes to a loan’s term and instalment, the order of contract terms for retirees, and the cap on credit cards issued by local banks. The figures for those items have not been published.
Before you sign
Lenders must now prepare a full credit assessment for a retired borrower, showing the financial effect of the loan and how much of the net pension is left for the whole repayment period, and walk the customer through it before the contract is signed. Ask for that assessment, and look hard at the monthly figure you will be left with.
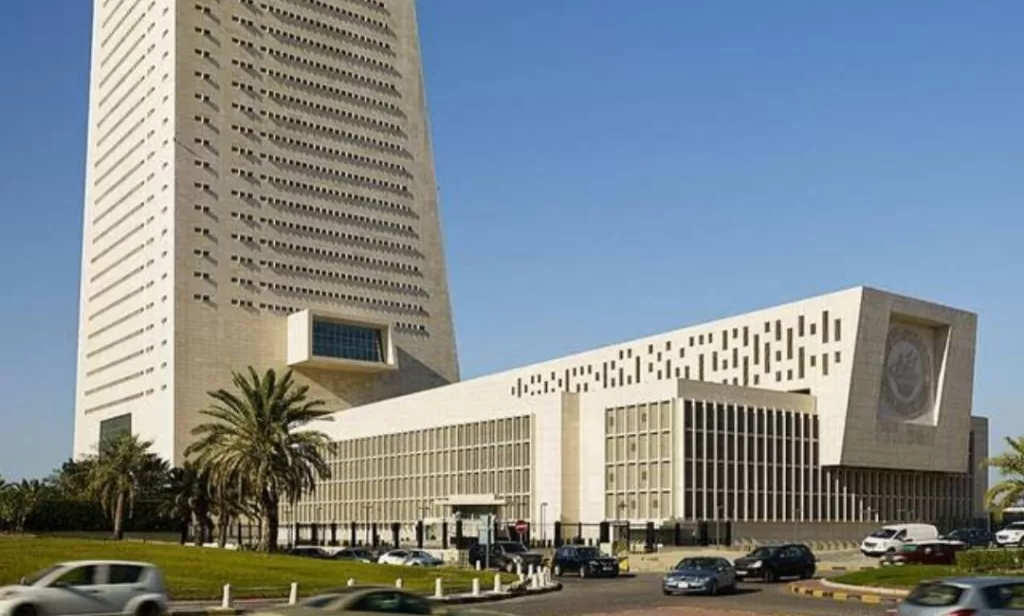
Photo: the Central Bank of Kuwait headquarters in Kuwait City. Photo by SamyrTotto, CC BY-SA 4.0, via Wikimedia Commons.
Source: Central Bank of Kuwait circular, via Al-Jarida and Al-Anba, 11–12 November 2026; the Central Bank’s FAQ page.
Kuwait One, once a week.
The most useful stories we published this week, in your inbox.
No spam. Unsubscribe anytime.